Masterful Strategy
Invest your time in what is most precious to you. Let us align your dreams to an accurate financial strategy.
What we offer

Financial Planning
Financial planning can be very tedious and difficult. That is why we are here, to help you through the whole proccess.

Managing Wealth
We enable you to build a meaningful life by offering our expertise in financial planning, retirement planning and financial management.

Estate Planning
We will assist you to implement the best possible structure to protect and preserve your most valuable assists.

Employee Benefits
As a professional financial planner and advisor focused on personalised service and care, we create value to enable a meaningful life to employers.
Start planning for your retirement
At Ultima, we equip you to plan for the future. Go to our retirement calculator to see if you are on track for your retirement.
About Ultima
Ultima Financial Planners enables you to build a meaningful life while enjoying lifelong peace of mind by partnering with you in your financial journey.
We do this by fostering a lifelong relationship with you – our client – focusing our attention on your long-term financial requirements that will enable you to build a meaningful life. It is our mission to inspire and assist you to live your dream by achieving financial freedom through dynamic financial planning, retirement planning and wealth management.
In providing you with pertinent financial advice based on more than 40 years combined experience, we utilise robust, tried-and-tested advising and decision-making processes, while our information is gathered through incisive analysis of in-depth investigation into financial markets, the economy and investments.
Our strength lies in the combination of our expertise in financial planning and devotion to you – our client – and the capability in helping you to implement well-considered decisions in a cost-effective manner. We care about your future and continue to add value to your life as we journey together.
Over the past 20 years, Ultima has grown into a reputable brand and financial partner. We are trusted for our expertise, distinguished and personalised service. We truly care about your future, helping you to build a meaningful life and enjoy lifelong peace of mind.
Testimonials
Johan Du Plessis
Senior Manager HR, ZZ2
- August 17, 2020
Ultima have assisted the ZZ2 Pension Fund Committee and members of the Fund to make informed and value driven decisions through their in depth analyses, financial models and comprehensive planning and available solutions. We value Ultima’s advice and service as this contributes towards ZZ2’s goal of creating a home for all our employees.
Ally Tloubatla
- August 14, 2020
World-class service. Ethical, proficient and highly professional.
Alfons de Witte
- August 14, 2020
I have been dealing with Ultima Financial Planners for the past 20 years and received good quality advice. I have complete peace of mind. I have been on pension for 17 years and are now living a better life when I started on pension.
Karen Pretorius
- August 14, 2020
It is hard to find the words to express my appreciation of and my gratitude to Ultima for their invaluable financial advice and guidance over the past few years. They were incredibly professional from my first phone call, the friendly reception upon arrival, as well as every aspect of the business I have done with them. As far as I am concerned, Ultima go way above and beyond expectations.
Prof. Piet Ankiewicz
- October 7, 2024
I have always been impressed with Ultima’s client care, exceptional business ethics, and integrity, which are rare in a world where such values are becoming increasingly unimportant. I appreciate Ultima’s active planning and management, during which planners and clients can get to know each other’s investment philosophies to adapt and achieve their financial goals based on their specific needs in the long term.
Lukas Rautenbach
- August 20, 2026
Ek is nou al meer as twintig jaar ‘n tevrede klient van Ultima en kry deurentyd professionele, akkurate en vriendelike advies en persoonlike diens. Ek het al verskeie vriende en familie na Ultima verwys en sonder uitsondering is hulle ook tevrede kliente. As gevolg van my vertroue in die Ultima eienaars en personeel is ek gemaklik dat my beleggings by hulle na behore bestuur word.
Testimonials
Johan Du Plessis
Senior Manager HR, ZZ2
- August 17, 2020
Ultima have assisted the ZZ2 Pension Fund Committee and members of the Fund to make informed and value driven decisions through their in depth analyses, financial models and comprehensive planning and available solutions. We value Ultima’s advice and service as this contributes towards ZZ2’s goal of creating a home for all our employees.
Ally Tloubatla
- August 14, 2020
World-class service. Ethical, proficient and highly professional.
Alfons de Witte
- August 14, 2020
I have been dealing with Ultima Financial Planners for the past 20 years and received good quality advice. I have complete peace of mind. I have been on pension for 17 years and are now living a better life when I started on pension.
Karen Pretorius
- August 14, 2020
It is hard to find the words to express my appreciation of and my gratitude to Ultima for their invaluable financial advice and guidance over the past few years. They were incredibly professional from my first phone call, the friendly reception upon arrival, as well as every aspect of the business I have done with them. As far as I am concerned, Ultima go way above and beyond expectations.
Prof. Piet Ankiewicz
- October 7, 2024
I have always been impressed with Ultima’s client care, exceptional business ethics, and integrity, which are rare in a world where such values are becoming increasingly unimportant. I appreciate Ultima’s active planning and management, during which planners and clients can get to know each other’s investment philosophies to adapt and achieve their financial goals based on their specific needs in the long term.
Awards


Awards
Blog
- October 29, 2026
- Financial Planning, Saving & Investing
“Wealth is not about having a lot of money; it’s about having a lot of options.” (Chris Rock)
Being financially literate isn’t about having an accounting degree, making sense of stock charts, or knowing how to decipher economic jargon. In fact, financial literacy has very little to do with high finance at all.
The real test of financial literacy is your ability to make decisions about your money. Do you understand how financial products work, the ways in which money moves through your life, and how choices you make now affect your future?
To gauge where you stand, here’s a simple five-question diagnostic test that highlights key financial ideas that everyone should understand.
1. Do you know the true cost of debt, not just your monthly repayments?
If you have taken out a loan to buy something, do you know what total rand amount you are paying over the life of that loan?
Whether purchasing a new couch or a new home on credit, the number most people focus on is the monthly instalment. This is the figure they use to judge whether it’s affordable or not.
This is not wrong. If you are taking out a loan, you should be sure of how that number fits into your monthly budget. But someone who’s financially literate also calculates what they will be paying over the full term of the agreement, and whether it’s worth it. They understand how compound interest works against them on high-interest credit cards, store accounts, and personal loans.
If you know your loan’s interest rate, initiation fees, monthly admin charges, and ultimate repayment total, you are making truly informed choices.
2. Could your household survive a financial shock without taking on more debt?
We all like to think that it won’t happen to us, but financial setbacks like an unexpected retrenchment, a major vehicle repair, or a big medical expense can hit at any time. Those who are financially literate know this, and prepare accordingly.
They appreciate that there’s a difference between asset wealth and immediate liquidity. Can you access a large amount of cash quickly and without impacting your future plans? You don’t want a sudden R15,000 emergency to force you to rely on a high-interest credit card or personal loan, or to dip into your retirement savings.
Financially literate people have an accessible emergency fund that covers three to six months of essential living expenses, protecting their long-term wealth from short-term disruptions.
3. Are your long-term savings outstripping inflation?
Many South Africans make the mistake of leaving large amounts of cash in savings accounts or fixed deposits because it feels “safe”. But they don’t consider how inflation acts as a silent tax, systematically eroding their purchasing power year after year.
Being financially literate means understanding the relationship between risk, return, and time. It means knowing that to build real long-term wealth, your money must be invested in compounding growth assets such as shares that comfortably beat inflation over time.
4. Are you taking advantage of South Africa’s tax incentives?
It’s not just companies and the mega wealthy that need to be tax efficient. Everyone should be thinking about how they can make the most of the few “free lunches” that the government offers us.
Do you know the annual limit for contributions to your tax-free savings account, and are you using it? Do you understand how contributions to a pension, provident fund, or retirement annuity reduce your taxable income, effectively securing you a tax refund from SARS?
Leveraging these structures ensures you retain and can reinvest more of your hard-earned money.
5. Can you write down the main elements of your monthly cash flow?
Financially literate people know that a high income does not guarantee financial security. Many people fall into the trap of increasing their expenses at, and often above, the rate that their income grows.
Do you know what income you get into your bank account every month after deductions? Do you have a good sense of your fixed obligations like bond payments, insurance and other debit orders and how much discretionary spending that leaves you with? And do you pay yourself first by automating your savings on payday rather than just hoping to save what’s over at the end of the month?
How did you score?
If you answered “no” to two or three of these questions, don’t see that as a failure. See it as a roadmap to improving your financial literacy. This isn’t about a static test that you pass or fail. It’s an ongoing process of developing self-awareness and good financial habits.
Being financially literate doesn’t mean knowing the answer to every financial question. It’s about knowing enough about your own finances to have meaningful conversations with us and to ask questions when you don’t understand something. Our door is always open.
Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.
© FinDotNews
- October 29, 2026
- Financial Planning
“The whole is more than the sum of its parts.” (Aristotle)
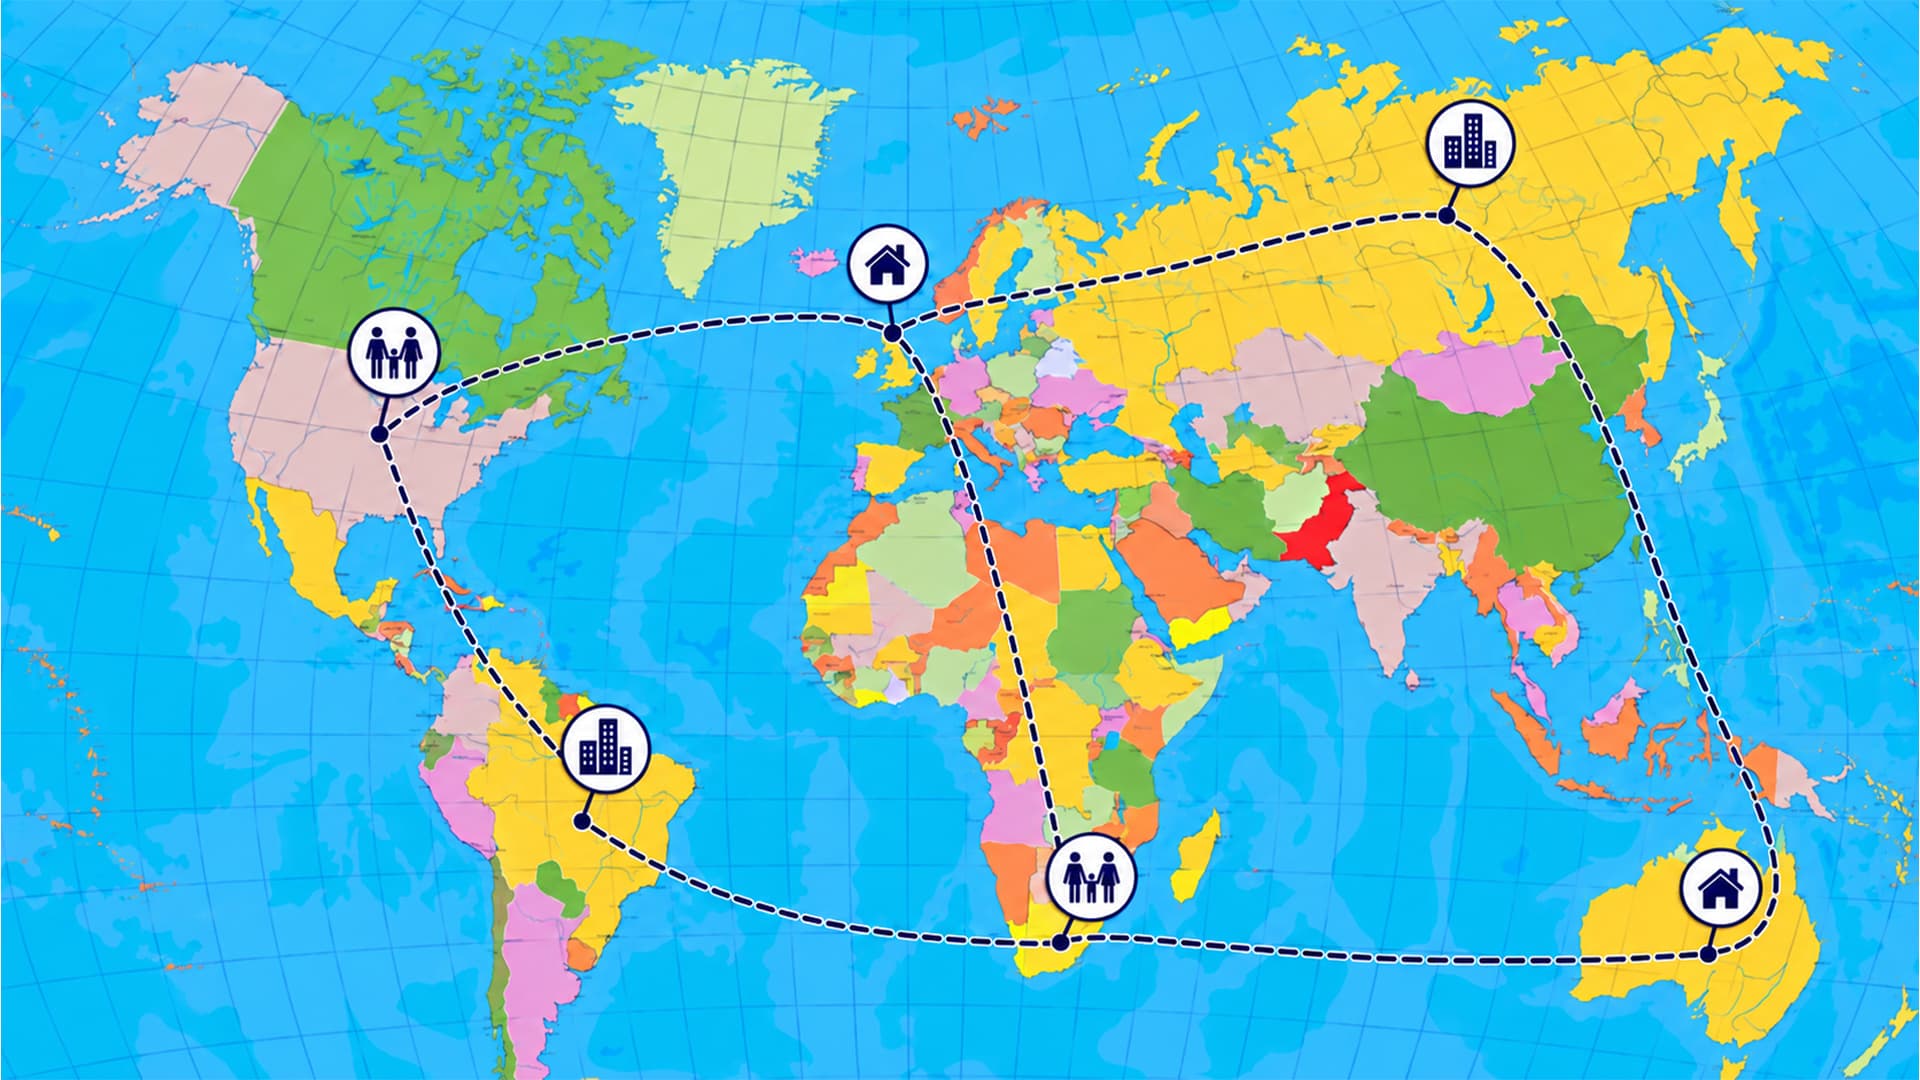
A family may have children studying in London, building businesses in Dubai, holding investments in Switzerland and planning retirement in Australia, while the family trust itself sits in an entirely different jurisdiction.
Structures like these are no longer unusual. Wealth has become increasingly international, and families have also become more geographically dispersed. Different generations may live under different legal systems, tax regimes and cultural influences. Over time, this changes not only how wealth is managed, but the demands placed on those responsible for looking after it.
When wealth crosses borders
International structures can look deceptively simple on paper. A trust may sit at the centre of investment portfolios managed abroad, operating businesses in another country and property holdings spread across several jurisdictions. At the same time, beneficiaries may be building their lives thousands of kilometres apart.
The structure itself may not have changed, but what about the family? A child emigrates. A sister becomes a tax resident in another country. The next generation inherits an interest in the family business. A foreign property is purchased. Gradually, a structure that was entirely appropriate when it was established can become outdated.
For families with international connections, estate and trust planning cannot be regarded as a once‑off exercise.
The era of isolated advice is fading
No single adviser can be an expert in every jurisdiction, tax system, investment environment and family circumstance. International families may require input from financial advisers, trustees, tax specialists, lawyers and succession professionals in several countries.
The difficulty is not necessarily finding good advice, it’s making sure that the advice works together. Depending on your circumstances, we are often well placed to maintain the broader view. We understand your investments, retirement plans, estate‑planning objectives and family circumstances, and can identify when a decision in one area requires specialist input in another.
Where a trust forms part of the plan, we will often work closely with a professional trustee or trust company. The trustee brings specialist fiduciary expertise and responsibility for the trust itself, while we help ensure that the trust is considered within your wider financial affairs.
The exact relationship will differ from family to family. In some cases, a trustee may take a greater coordinating role; in others, we may do so. What matters is that someone retains sight of the whole picture and that the professionals involved communicate with one another.
Stability has a value of its own
International diversification is usually discussed in terms of investments, but globally connected families also need to consider the environment in which their wealth structures operate.
There is no single jurisdiction that will suit every family. You’ve got to consider the family’s particular circumstances, including where its members live, where its assets are held, and what the structure is intended to achieve.
For South African families, this is particularly relevant when children settle abroad or when significant assets are held offshore. Where a wealth structure is located can therefore become part of risk management.
A trust can’t do everything
There is also a part of wealth preservation that no legal structure can manage on its own. Families devote considerable attention to trusts, succession plans, investments and asset‑protection structures. Yet even well‑designed arrangements can come under strain when family members have very different expectations about wealth and the responsibilities that accompany it.
The next generation may inherit the assets without having experienced the years of work, risk or sacrifice that created them. Geographic distance can widen that gap further. A trust can protect assets and determine how they are administered or distributed, but it can’t automatically preserve understanding between generations.
This is where communication and family governance come into play. Families need opportunities to discuss why structures exist, what wealth is intended to achieve, and what responsibilities future beneficiaries may eventually inherit.
Choosing the right trustee
Where a trust is appropriate, choosing the right trustee is an important part of the wider planning process.
Technical competence is the starting point. Trustees carry serious legal and fiduciary responsibilities, and sound administration and compliance are non‑negotiable.
For an internationally connected family, however, experience also matters. Has the trustee dealt with families whose beneficiaries live in different countries? Do they understand the complications that can arise when residency changes? Do they know when an issue falls outside their expertise and requires specialist advice?
Judgement can be harder to assess, but it is equally important. Trustees may have to balance the interests of different beneficiaries, deal with sensitive family circumstances and make decisions whose consequences will only become apparent years later.
Families should also consider continuity. A trust may survive its founder and remain in place for several generations. The relationship is therefore not simply with the individual sitting across the table today, but with the organisation and people who may eventually take their place.
If your family spans multiple jurisdictions
If you have family members living in different countries, or assets held across borders, we can help you assess whether your current structures still serve their intended purpose. And we can assist you in selecting a suitable trust company if needed.
Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.
© FinDotNews
- October 29, 2026
- Financial Planning, Saving & Investing
“Simplicity is the ultimate sophistication.” (Leonardo da Vinci)
Few people deliberately set out to build a complicated investment portfolio. It tends to happen over a lifetime.
A retirement fund is left behind after changing jobs. You open a tax-free savings account. A property does particularly well. There may be shares inherited from your parents and an investment made years ago on a buddy’s recommendation.
None of these decisions looked especially troublesome at the time. But years later, you may own a substantial collection of assets without ever having considered whether they still belong together.
Good investments can make a bad combination
Most of us judge an investment on its own merits. Is the fund performing well? Has the property increased in value? Has the share price risen? Those are reasonable questions, but they tell only part of the story. An attractive new fund might invest in many of the same companies already held elsewhere. A successful shareholding can grow to represent far more of your wealth than originally intended.
This is how someone who considers themselves cautious and sensible can end up with a risky portfolio. Nothing necessarily went wrong, the portfolio simply evolved without you noticing.
We become attached to what we own
Tidying up sounds straightforward until human behaviour enters the picture. Investments that have been around for years tend to acquire a certain permanence. If they aren’t causing an obvious problem, there’s little urgency to review them. The original reason for buying them may have disappeared long ago, but inertia is powerful.
Investments that have disappointed us are difficult for another reason. Selling turns a paper loss into a real one. Holding on allows us to believe that the investment might recover, which helps explain why people sometimes retain poor performers for far longer than they intended.
Winners bring their own complications. If a particular share or fund has delivered handsomely for years, reducing your position in it can feel strangely illogical. Yet its very success may have left too much of your wealth dependent on one company, sector or market.
Money isn’t always the deciding factor either. An inherited shareholding, family property or interest in a business can carry history and sentiment. Of course, there may be excellent reasons for keeping it. The important thing is to recognise the difference between actively choosing to retain an asset and never having questioned it.
Then life changes
Portfolio weaknesses tend to remain hidden while circumstances remain unchanged. But retirement often exposes them. For decades, the main objective may have been to accumulate capital. Now some of that capital must produce income. Liquidity becomes more important, and a sharp market fall is harder to shrug off when there are fewer earning years available to rebuild what’s been lost.
Suddenly, the individual investment statements are less useful than the combined picture. You may own five funds and discover that several hold many of the same companies. Two fund managers may favour similar markets. Different advisers may each be doing a perfectly competent job, but only within the slice of the portfolio they can see.
Other questions start to matter too. How much is invested in equities? Is there more offshore exposure than intended? Where are the largest concentrations? How easily could capital be accessed? What level of income could the portfolio reasonably support? Until everything is brought together, some of those questions will be impossible to answer.
Start with a blank sheet of paper
There’s no need to respond to complexity with a wholesale clean-out. In fact, doing so could be expensive. Some older investments have guarantees worth preserving. Selling assets with large, accumulated gains may create tax consequences. A private business or property cannot necessarily be sold neatly or quickly, and family assets may deserve different treatment from an ordinary investment fund.
A better starting point is simply to map what is there. Then look at each significant holding in the context of everything else. Why do I own this? What does it contribute? What risk comes with it? Do I already have another investment doing much the same job?
One question
One question cuts straight to the chase: If I had the money in cash today, would I buy this investment again? A “no” doesn’t mean it should immediately be sold. Tax, timing, and other considerations still matter. But it is a useful signal that an investment deserves another look.
For people with substantial wealth, some complexity is unavoidable. Businesses, property, offshore assets, and retirement investments do not fit neatly into a single structure, nor should they have to. The aim is not to own fewer things simply for the sake of it, it’s to know why you own them.
Please contact us if you’d like to review your portfolio, including every asset that you own.
Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.
© FinDotNews

- October 29, 2026
- Bonds, Equities, Global, Markets, South Africa
“In the short run, the market is a voting machine but in the long run it is a weighing machine.” (Benjamin Graham)
Benjamin Graham’s renowned quote captures the market’s response to October’s Medium-Term Budget. The father of value investing can’t have been surprised as bond investors weighed the budget’s credibility years into the future, while equity investors were voting on this year’s GDP growth downgrade.
What the budget delivered
Bond investors got what they care about most. The Medium-Term Budget Policy Statement introduced the fiscal anchor, backed it with a bond buyback and trimmed weekly auction supply, all of which reduce the risk that government borrowing keeps outrunning its ability to pay. The 2035 bond yield fell about 14.5 basis points to 8.59%, while the 2048 yield dropped around 18 basis points.
Why bonds applauded, and shares did not
- Bonds price sovereign credit, supply and real yield. A credible budget improves all three, and with the repo rate at 7.25% and inflation at 4.5%, South African bonds still offer a generous real return.
- Equities price in growth and earnings, and the budget offered little new on either front, with the economy contracting 0.2% in the second quarter and 2026 growth forecast reduced to 1.2% versus February’s 1.6% estimate.
- With the JSE largely driven by global factors, gold and platinum miners, Naspers, Prosus, and Tencent responded to metal prices, while big-tech sentiment mattered most. As a result, the JSE Top 40 slipped just 0.4% on budget day, then fell more than 1% the following day as chip, metals, and oil sentiment drove the decline.
- Consumer-facing shares retreated as a lower growth rate this year, combined with the fuel-price shock and high borrowing costs, is expected to weigh on household spending, and a better bond market won’t alleviate spending conditions overnight.
The broader backdrop
Globally, the Federal Reserve has lifted rates to a target range of 3.75 to 4.00%, US inflation is 3.7%, and oil is trading at US$100 to $110 on the ongoing Strait of Hormuz disruptions. The US 10-year yield near 5.3% is pressuring stretched valuations, and October’s sell-off in AI and chip shares shows how concentrated the rally has become.
At home, the JSE has declined about 7% year-to-date after surging 39% in 2025, while bonds were considered relatively cheap for the risk, allowing yields to fall on the day.
How to navigate the risks
- Stay diversified. Bonds and equities are answering different questions, so holding both is the point, not a compromise.
- Do not chase the relief rally. Fiscal credibility is earned over years.
- Remember that inflationary pressure still predominates globally, so the risk of higher rates going forward remains to the upside.
- Keep equity exposure tied to goals and time horizons, not to the budget headline.
The bottom line from October was that a good budget lowers the cost of South Africa’s debt. But it does not, on its own, raise the earnings of its companies.
*All facts and figures accurate at time of writing.
Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.
© FinDotNews
- September 30, 2026
- Retirement Planning
“The future belongs to those who believe in the beauty of their dreams.” (Eleanor Roosevelt)
A very real retirement risk
You may have heard about the dangers of retiring into a falling market, as it can have a persistent negative effect on your portfolio. This is known as sequence-of-returns risk, and it’s one of the most important risks to understand as you move from investing money to living off your savings.
While much of the discussion around sequence risk focuses on what happens when markets fall at the wrong time, the reverse can also be true: a favourable sequence of returns can leave you in a far stronger position than your original retirement plan assumed.
Let’s dig a little deeper
Consider two investors who retire with equal investments. They withdraw the same amount over a 30-year period and receive the same average return on their investments. One would expect that they end up in the same position, but the reality is that the outcomes may be quite different.
- If one investor enjoys several strong investment years early in retirement, their portfolio has an opportunity to grow before regular withdrawals begin to make a significant dent in the capital. That larger amount of capital then continues to generate returns in later years.
- The other investor may experience several weak years at the beginning of retirement. Their withdrawals are being taken from a portfolio that has already fallen in value, leaving less capital available to benefit when markets eventually recover.
The average return is only part of the story. The order in which those returns occur can have a significant effect on how much capital remains available later in retirement – and ultimately, how much can be passed on to the next generation.
When sequence risk works in your favour
Sequence risk has built up an almost entirely negative reputation. But there’s another side to the story that doesn’t get a lot of attention. What if you are very lucky with the sequence of returns and you retire into a bull market? You may end up with a lot more than expected.
A retirement plan designed primarily around avoiding the risk of running out of money can leave people psychologically stuck in protection mode. Even when their financial position has become stronger than expected, they may continue to spend cautiously, postpone experiences or keep accumulating wealth because spending still feels like a threat to their security.
The opportunity cost of not enjoying your capital once you realise you’ve lucked out is huge. Think of losing the freedom to travel (especially to family overseas), pursue other hobbies, and help your children and grandchildren financially. These are particularly valuable in the early years of retirement, when you hopefully have sufficient health/energy to live life to the full.
If you’ve always dreamed of buying a house at the beach, and the numbers show you can afford it … Do it now, before health issues kick in or the kids emigrate!
When it comes down to it, the value of your capital is not only measured by numbers, but by what the funds enable you to do. When wealth outgrows the plans, why not make intentional decisions to enjoy it rather than be shrouded in fear?
The bottom line
Sequence risk has two sides. The wrong sequence of returns can threaten a retirement plan; the right one can create opportunities that were never anticipated. Good retirement planning prepares you for both. It is not simply about protecting your capital against what might go wrong but recognising when things go right, and having the freedom to make the most of it.
Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.
© FinDotNews
- September 30, 2026
- Estate Planning
“Almost every funeral is attended by at least a few people whose funerals the person being buried thought he or she would attend.” (Mokokoma Mokhonoana)
When South Africans think about the death of a loved one, many focus on the funeral. Funeral cover is the most widely held insurance product in the country. However, we tend to be much less well prepared for the financial, administrative, and emotional aftermath that follows the burial.
Capital Legacy’s recently launched Estate Readiness Index (ERI), showed a significant gap between what families expect during this time, and what actually happens. The index gave the nation a sobering preparedness score of just 50 out of 100 when it comes to estate planning.
Here’s why this matters. Estate planning is not merely a morbid end-of-life discussion. It is a vital, proactive conversation about household resilience.
The danger of the three-month cash crunch
To begin with, the ERI survey revealed that 53% of families experienced severe financial pressure following a death. Of those, 66% faced a cash shortage within the first three months.
Mostly this happens because a death instantly alters a family’s financial machinery.
By law, bank accounts are frozen while the deceased’s estate is registered and processed. Yet, the monthly reality of debit orders for bonds, vehicle finance, and school fees continues to run. If an estate is “asset rich but cash poor” (meaning you own property but lack accessible liquid cash) your family may be forced into debt just to survive the transition period.
The misalignment of time and process
Compounding this financial pressure is a widespread misunderstanding of the legal timelines. More than half of the families surveyed by Capital Legacy expected the estate administration process to be wrapped up within six months. Unfortunately, only 28% of families actually had this experience.
Nearly half of the respondents waited between one and two years. The maze of Master’s Office backlogs, complex paperwork, and conveyancing delays can cause real friction. When a family is already grieving, these issues also create immense emotional strain.
What’s more, in 54% of cases the burden of wrapping up the estate fell to grieving family members, rather than professionals. Many South Africans overlook how much of a weight it is for a bereaved spouse to navigate SARS tax clearances and government bureaucracy.
These challenges are also often exacerbated by family politics. In the ERI survey, 42% of families reported falling into disputes while the estate was being finalised, often over money, property, and differing views on the deceased’s wishes.
A blueprint for household resilience
These realities illustrate why estate planning should be approached not just from the perspective of how your wealth is passed on, but rather how your family is protected.
Here is how you can build a resilient estate plan today:
- Prioritise liquidity: Ensure you have life insurance policies that pay out directly to a nominated beneficiary (like your spouse). This bypasses the frozen estate, providing immediate, accessible cash to keep the household running.
- Plan for hidden costs: Your estate is responsible for settling all outstanding debt, alongside executor’s fees (which can reach 3.5% plus VAT of the gross estate), Master’s fees, and conveyancing costs. Structure your estate to cover these expenses so your executor isn’t forced to sell off assets.
- Draft a valid, clear will: A poorly drafted will can be worse than no will at all. Ensure it is legally sound and unambiguously outlines your wishes to prevent familial conflict.
- Protect minor children: If you have minor children, set up a testamentary trust within your will. If you die without a will, any funds due to minor descendants may be paid into the government-run Guardian’s Fund. This will complicate access to the money meant for your child’s upbringing.
- Create a “life file”: Consolidate all critical information into one secure place. Include where your original signed will is kept, bank account details, policy schedules, and passwords. Make sure your family knows exactly where to start.
Ultimately, leaving a legacy isn’t just about the assets you leave behind – it’s about the state in which you leave them. By taking comprehensive steps today, you shield your loved ones from unnecessary financial distress and administrative chaos, giving them the space they truly need to heal.
Please do chat to us about your estate plan.
Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.
© FinDotNews
- September 30, 2026
- Financial Planning, Saving & Investing
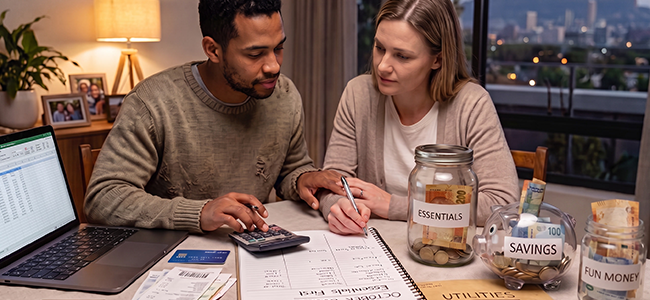
“A budget is telling your money where to go instead of wondering where it went.” (Dave Ramsey, author of The Total Money Makeover)
With living costs rising, many households are already looking more closely at their expenses. The temptation is to tackle the biggest debit orders first. A better starting point may be to ask: “Is my money still going where I actually want it to go?”
The spending you’ve stopped seeing
Unnecessary spending is often remarkably ordinary.
Subscriptions renew. A gym membership hangs around long after the enthusiasm for going to the gym has disappeared. Data packages, cloud storage, bank charges, and memberships continue in the background, largely because none of them seems significant enough on its own to worry about.
Go through three months of bank and credit-card statements and you may be surprised by what you find. It isn’t necessarily one extravagant purchase that makes the difference, but the combined cost of things you hardly notice paying for.
If that adds up to R1 500 per month, it amounts to R18 000 over a year. Suddenly the numbers become more interesting. That money could go towards an emergency fund, an investment, a holiday or paying down expensive debt.
Larger discretionary purchases deserve some thought too. There is nothing wrong with an expensive car, a designer handbag or a good restaurant if you can afford it and it genuinely matters to you. The question is whether you still value what you’re paying for, or whether your income, peer group or professional status has gradually changed your idea of what is “normal”.
Don’t begin with the important stuff
When household finances are under pressure, large monthly debit orders are often the first to come under scrutiny. Life and disability cover, medical scheme contributions, and voluntary retirement savings can look particularly expensive when added to a collection of smaller discretionary costs.
They are probably doing far more important jobs.
Before cutting insurance, go back to the reason you took it out and ask whether that risk still exists. Find out what you would lose before changing medical cover. If you are considering reducing voluntary retirement contributions, look at the effect on the retirement plan rather than simply the saving on next month’s debit order.
Of course, none of these costs is sacred. Circumstances change, products become inappropriate and financial plans need to be reviewed. The important distinction is between removing an expense you no longer need and giving up something valuable just to get some short-term breathing room.
What is your money keeping you from doing?
Picture a nurse in her fifties. She earns a decent salary, has always been fairly careful with money and would love to spend more time in Kruger. Yet the money for those trips never seems to be there.
Eventually, she goes through a few months of bank statements. There is no lavish purchase to blame. Over the years, her lifestyle has simply collected expenses. Some are useful, some have become habits and others she barely cares about anymore.
She leaves her medical scheme, insurance and retirement savings alone and starts trimming elsewhere. The money she saves goes into a travel account. Nothing dramatic happens to her day-to-day life, except that the wildlife trips she kept putting off start becoming affordable.
When extra money doesn’t feel like extra money
Budgets are not only for times when money is tight. They can be surprisingly revealing when income has been rising for years.
Spending has a habit of catching up with you. The occasional treat becomes routine; the car gets upgraded and expenses that once felt indulgent gradually become part of everyday life. A person can be earning considerably more than they did five or ten years ago without feeling much more financially secure.
Enjoying the rewards of earning well isn’t the problem. It becomes a problem when spending rises almost unnoticed and saving or investing is repeatedly postponed until the next increase.
This is also where a spending review becomes useful. Your financial planner needs to know what your lifestyle actually costs, not what you think it costs. That number influences how much cash you need in reserve, how much you can realistically invest and, eventually, how much income your capital may need to provide in retirement.
Pay less for what matters less
There is no right amount to spend on restaurants, holidays, cars or entertainment. One person’s extravagance may be another person’s great pleasure.
Nor should a budget strip all the enjoyment out of today in the interests of a distant future. But it is worth finding out whether today’s lifestyle is absorbing money that could give you more choices later.
The bottom line
Look at the expenses that have become habits. Keep the financial commitments that still have an important job to do. And when you find money being spent on something you no longer particularly value, give it another job.
A budget doesn’t just tell you where your money has been going. It also begs the question: “Where would you rather it went?”
Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.
© FinDotNews
- September 30, 2026
- Market Update
“I can calculate the motions of the heavenly bodies, but not the madness of people.” (Sir Isaac Newton, after losing a fortune in the South Sea Bubble, 1720)
Newton’s post-South Sea Bubble lament in the 18th century feels timely again. This week, market historian Edward Chancellor warned in a Reuters column that the 2021 “Everything Bubble” is back, but with far greater downside risks.
What is the Everything Bubble?
An Everything Bubble forms when easy money lifts almost every asset at once, from shares and crypto to new listings. Prices then rest less on fundamentals than on the belief that someone will pay more for anything in the future. In 2021, Janus Henderson’s Richard Bernstein listed five warning signs months before US equities peaked. Today, all five are flashing again:
- Liquidity: Financial conditions remain almost as loose as at their 2021 trough.
- Leverage: US margin debt is at a record, and zero-day options, leveraged same-day options contracts, make up about half of US options turnover.
- New speculators: Retail apps now offer tokenised private shares and access to prediction markets, blurring investing and gambling.
- New issues: SpaceX raised a record US$75 billion in June, with OpenAI and Anthropic potentially to follow, and SPACs are back.
- Turnover: Average daily US share trading topped US$1 trillion for the first time in January.
Concentration makes this period more dangerous than previous Everything Bubbles. Circular financing among AI players is an ongoing concern, as it depends on continuously accelerating revenue growth, so even a modest slowdown could shake the sector’s performance. The US market is expensive. The S&P 500’s Shiller CAPE, considered the best measure of how expensive stocks are, sits near 41 versus a dot-com peak of 44.
More than the September effect
September is historically the worst month for stocks, but this year’s market jitters have firmer foundations: sticky inflation and rising interest rates. On 23 September, the South African Reserve Bank (SARB) unanimously raised the repo rate by 25 basis points to 7.25%, citing an intensifying fuel-price shock. Bubbles tend to burst when rates rise, and money gets more expensive. This is the main risk investors face for the rest of 2026 and into 2027.
How to navigate the risks
- Stay invested. J.P. Morgan found that an investor who bought at every major market peak since 1990 still ended up with 3.6 times her money (compared with 1.6 times her money if she invested in cash).
- Avoid leverage, which can turn a correction into a forced sale.
- Match money to goals. Keep near-term needs in cash and short-term bonds; let long-term capital ride out volatility.
Markets can stay irrational for longer than investors can stay solvent. The best defence is a plan that does not depend on calling the top.
Please speak to us before making any rash decisions!
*All facts and figures accurate at time of writing.
Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.
© FinDotNews
- August 28, 2026
- Retirement Planning
“One mustn’t dream of one’s future; one must earn it.” (Carlos Ruiz Zafón)
In the past, it was not uncommon for someone to work for the same company for their whole career. That is extremely rare today. In the modern working world, you may move to a new employer every two or three years.
This is great for flexibility and career progression, but it requires you to be highly proactive about your pension savings. If you have been paying into a pension or provident fund through your employer, you need to make a decision about what to do with that money every time you leave.
The old rules vs. the new reality
Before September 2024, the choice was relatively straightforward: you either took your entire fund as a cash payment or you kept it invested. However, the implementation of the “two-pot” retirement system has changed how resignation withdrawals work.
Under this legislation your retirement savings are divided into three components, each with different rules:
- The vested component: This is any money you saved up until 31 August 2024, and the old rules still apply here. You can withdraw this money in full when you resign, but it will be taxed aggressively.
- The savings component: This contains one-third of your retirement contributions made since 1 September 2024. You can withdraw from this pot when you resign (even if you’ve used your annual withdrawal limit, provided you close the account), but it will be heavily taxed.
- The retirement component: This holds two-thirds of your contributions made since 1 September 2024. By law, you cannot cash this out when you change jobs. This money must be preserved to buy an annuity income when you retire.
Think twice before cashing out
While you can access your vested and savings components when you resign, that doesn’t mean you should. In fact, taking the cash is rarely the right choice.
Firstly, SARS taxes these withdrawals heavily to discourage you from raiding your nest egg. Secondly, if you take out your available savings, that portion of your retirement fund effectively goes back to zero. You might think you can always make this up, but remember that any investor’s most powerful ally is time.
The longer your money stays invested, the more it benefits from compound interest. Time is not something you ever get back.
2025 data from Sanlam Corporate indicates that to afford a comfortable retirement, the average South African may need to work until they are 80 years old. And the primary driver of this shortfall is people cashing out their pension savings when changing jobs.
When you do this, you are effectively taking money from your future self.
Four ways to keep your money invested
To secure your future, it is therefore almost always better to preserve your savings when changing jobs. You have four tax-free ways to do this:
- Keep it in your current fund
If you do not explicitly instruct your HR department otherwise, your savings will automatically be left exactly where they are. You will earn the same growth as other members, although you will no longer be able to make monthly contributions. - Transfer it to your new employer’s fund
If your new employer offers a company pension or provident fund, you can transfer your balance across to the new fund. This allows you to keep all your savings in one place, making them easier to manage and monitor. However, you may want to work with a financial advisor (that’s us) to compare the fees and historical performance of the two funds to see which serves you better. - Transfer it to a retirement annuity (RA)
In an RA you get to choose your underlying investment funds and you can easily make additional contributions over time. Just be aware that you cannot access the funds in your vested or retirement components until you turn 55. - Transfer it to a preservation fund
If you transfer to a preservation fund, you retain the right to make one pre-retirement withdrawal from your vested component before the age of 55. This can act as a vital safety net if you ever face a severe financial crisis. The drawback is that you cannot make any additional contributions.
Each of these options has pros and cons, and it’s often best to get advice when making a decision. After all, this money is your future. Changing jobs? Speak to us before you make any decisions.
Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.
© FinDotNews
- August 28, 2026
- Financial Planning
“There are only two lasting bequests we can hope to give our children. One of these is roots, the other, wings.” (Johann Wolfgang von Goethe)
When affluent families gather to discuss their long-term plans, the script is normally pretty predictable. They talk about things like investment portfolios, trust structures, succession plans, and tax legislation. But one question is seldom asked.
Is our family’s citizenship strategy fit for the future?
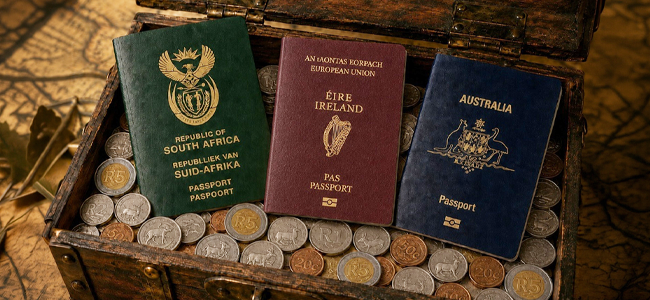
For many years, citizenship was little more than an administrative fact. It determined where you voted and which passport you carried through an airport. All that’s changed. Increasingly, globally connected families are recognising that citizenship is more than a legal status. It’s a strategic asset capable of expanding opportunities, protecting future generations and strengthening a family’s resilience.
These days, companies operate across continents, children study at universities around the world, and family members often build careers in countries their grandparents can’t even pronounce. At the same time, geopolitical tension, changing tax regimes, economic volatility and evolving immigration policies have shown that stability can no longer be taken for granted.
Against that backdrop, we are beginning to redefine wealth itself
For decades, financial planning has focused on preserving capital. Diversification meant spreading investments across different asset classes, sectors and geographical regions to reduce risk. It was built on a simple principle: never allow too much of your family’s future to depend on a single outcome.
In recent years many families have diversified their investment portfolios internationally. But relatively few have asked whether the same principle should apply to something as valuable as the legal rights and opportunities available to future generations.
Unlike shares, property or private businesses, citizenship cannot be measured by annual returns or quarterly performance. It produces no dividend, pays no interest and appears nowhere on a balance sheet. Its value lies elsewhere.
Citizenship creates optionality
Citizenship is the key to a future where citizens can study, build careers, start businesses or retire visa-free. It can also affect access to health care, legal protection and political stability. It’s like insurance: you don’t know its value until things suddenly change.
The COVID-19 pandemic was a sobering reminder of how fragile international mobility is. Borders slammed shut virtually overnight, travel rules kept shifting, and continents separated families.
For families trying to preserve wealth across generations, the planning conversation is no longer confined to where capital should be invested. It should also include where future generations may wish—or need—to build their lives.
This is not to say that every family needs multiple citizenships, or that citizenship should ever be a status symbol. Instead, it deserves the same disciplined thought we give every other major family decision: What risks do we need to take on today, and what opportunities do we want to hold for tomorrow?
A governance conversation
Questions that once seemed unusual are becoming increasingly relevant.
- Will future generations have the flexibility to establish themselves where opportunity exists?
- Have cross-border succession issues been considered?
- Are family structures capable of supporting an increasingly international family, or are they still designed around outdated assumptions?
Without shared values, thoughtful governance and careful preparation, additional citizenship merely gives people more places to make poor decisions. The most enduring families understand that true legacy is never created by documents alone. It is created by preparing people to use the opportunities they inherit wisely.
Perhaps that is how we should begin to think about citizenship. Not as an immigration decision, a tax technique or simply another passport, but as a strategic investment in a family’s future.
Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.
© FinDotNews
- August 28, 2026
- Fixed Income, Markets, South Africa
“I used to think that if there was reincarnation, I wanted to come back as the president or the pope. But now I want to come back as the bond market. You can intimidate everybody.” (James Carville, 1993)
James Carville’s three-decade-old quote about the bond market’s intimidating power has never felt more relevant. Since mid-August, bond market investors have been reasserting themselves as the ultimate arbiters of fiscal discipline, and the US government is feeling their wrath.
The 30-year US Treasury yield reached 5.34% on 18 August, its highest level since 2007. The 10-year yield followed at around 4.74%. This shows investors are demanding greater compensation for holding US government debt, as a historically large deficit, persistent inflation and a fresh wave of AI-linked corporate bond issuances compete for the same pool of capital.
Bond vigilantes, reawakened
The US Treasury Department reacted quickly. On 19 August, Secretary Scott Bessent doubled the department’s bond buybacks, from $2 billion to at least $4 billion, targeting longer-dated debt to steady the market. Yields eased only slightly, highlighting that the underlying drivers are structural:
- US debt issuance is rising faster than natural demand can absorb it.
- US inflation has stayed above target for five consecutive years.
- Corporate borrowing to fund the AI buildout is now competing directly with sovereign debt for investor capital.
The sell-off wasn’t confined to the US: Germany, France, Japan and the UK experienced it too, confirming an old market adage that when the US sneezes, the rest of the world catches a cold.
Why South Africa hasn’t followed the script
A risk-off shift of this scale would typically push South African yields higher too, but the opposite happened. Its 10-year yield has fallen to around 8.5%, the rand has strengthened to roughly R16.00 to the dollar, its best level since February, and foreign investors bought a net R23.1 billion of local government debt in the first week of August alone. The dollar-funded rand carry trade returned 2.5% to 3.5% this month, the best of 22 emerging-market currencies tracked by Bloomberg. SA’s 7% repo rate, improving current account and fading geopolitical risk premium are driving this foreign interest.
What this means for portfolios
While SA benefited in August, history shows the tide can turn just as quickly. The truth is:
- Carry-trade inflows are not evidence of a structural re-rating, and can reverse quickly.
- A renewed US fiscal scare or Fed hawkishness would erode the rand’s advantage.
- Domestic credibility matters, and the SA Reserve Bank’s decision to hold interest rates in July dented it.
With this in mind, treat this month’s market tailwinds as a windfall rather than as a decoupling from the US bond market woes.
*All facts and figures accurate at time of writing.
Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.
© FinDotNews
- August 28, 2026
- Saving & Investing
“An investment in knowledge pays the best interest.” (Benjamin Franklin)
Private credit has become one of the fastest‑growing corners of global finance, attracting interest from pension funds, asset managers, and institutions worldwide. Even though this trend doesn’t require you to adjust your own investment strategy, it’s still valuable to understand what’s happening behind the scenes when a new asset class starts making headlines.
For many people, the term “private credit” still carries echoes of an older world: desperate borrowers, predatory lenders, and sky‑high interest rates. That image is outdated. Modern private credit is structured, institutional, and increasingly central to how businesses access funding. Understanding why it’s booming helps you stay informed, confident, and connected to the broader financial landscape.
What is private credit?
Private credit simply refers to lending that happens outside the traditional banking system. Instead of banks providing loans, private credit funds step in. These funds are run by professional managers and backed by investors such as pension funds, insurers, and asset managers.
The borrowers in private credit aren’t individuals, they’re businesses. Most are mid‑sized companies or specialised lenders that need capital to grow or support their own clients. These loans are formal, well‑structured agreements with proper oversight, handled by established businesses and professional lenders.
The forces driving the private credit boom
Private credit didn’t suddenly appear out of nowhere: it’s been building for years as the financial world has shifted. After the 2008 financial crisis, banks became far more cautious and tightened their lending rules, which left many businesses struggling to access funding. At the same time, investors were searching for better income options because traditional bonds offered very little yield for more than a decade. And while banks were becoming slower and more rigid, private credit funds were able to move faster, offer more flexible terms, and tailor their lending to the needs of growing businesses. For many companies, that combination of speed and flexibility made private credit an attractive alternative. As these trends unfolded, private credit naturally found room to grow.
Why this still matters for everyday investors
Private credit matters, even if you never invest in it, because it shows how financial markets adapt when traditional lenders pull back and new players step in. It also highlights how small and medium-sized businesses, which often struggle to access funding through banks, are finding new ways to grow. At the same time, institutions have been drawn to private credit because it offers steadier income and lower volatility than many traditional investments.
For individual investors, understanding trends like this reinforces the value of having a long‑term financial plan that isn’t swayed by every shift in global markets, but is strengthened by staying informed.
Clarity creates confidence
Private credit is booming because it meets real needs: for borrowers who want flexibility, and for investors who want yield. It’s structured, institutional, and increasingly transparent. While it’s not an asset class most individual investors need to pursue, understanding it helps you stay connected to the broader financial world.
Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.
© FinDotNews
Blog
- October 29, 2026
- Financial Planning, Saving & Investing
- October 29, 2026
- Bonds, Equities, Global, Markets, South Africa
- September 30, 2026
- Financial Planning, Saving & Investing
- September 30, 2026
- Market Update
- August 28, 2026
- Retirement Planning
- August 28, 2026
- Fixed Income, Markets, South Africa


Contact Ultima
Contact us
Physical Address:
Ground Floor, Block F, Glenfield Office Park, Corner Glenwood and Oberon Avenue, Faerie Glen, 0081
Telephone:
+ 27 12 348 1386
Fax:
+ 27 12 348 3706
Email:
Contact us
Contact info
Physical Address:
Ground Floor, Block F, Glenfield Office Park, Corner Glenwood and Oberon Avenue, Faerie Glen, 0081
Telephone:
+ 27 12 348 1386
Fax:
+ 27 12 348 3706
Email:
